
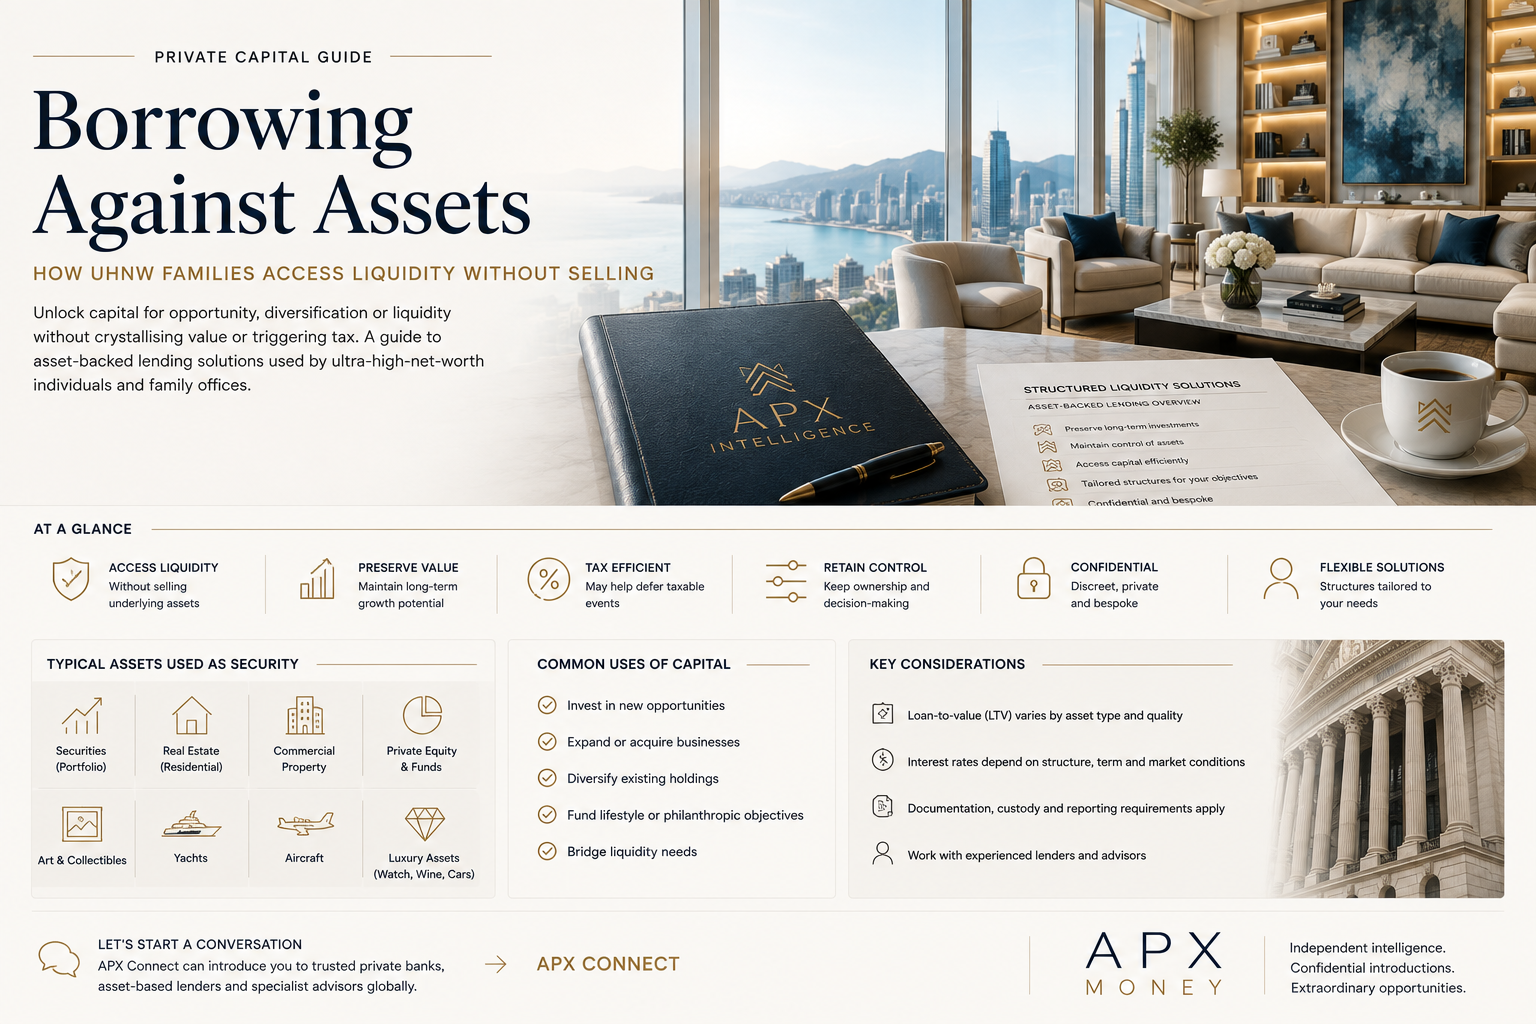
Borrowing Against Assets: How UHNW Families Access Liquidity Without Selling
An institutional advisory guide on securities-backed lending, Lombard facilities, real estate refinancing, luxury asset collateralisation, and structural risk mitigation.
Executive Summary
One of the great misconceptions surrounding substantial private wealth is that wealth and liquidity are the same thing. They are not. A founder may have hundreds of millions tied up in a business. A family may control valuable property, investment portfolios, aircraft, yachts, art and private-company interests while maintaining relatively modest amounts of idle cash. This creates a recurring family-office problem: How do you access significant liquidity without selling an asset you still want to own? For many UHNW families, the answer is borrowing. Public securities can support Lombard loans or securities-backed credit. Property can be refinanced. Specialist lenders may lend against aircraft, yachts and fine art. More complex private assets can sometimes support bespoke financing structures. Major private banks openly provide specialist lending against categories including art, aircraft and superyachts. Used intelligently, debt can prevent a forced sale, preserve strategic ownership and provide capital precisely when an opportunity appears. Used badly, it can transform an asset-price decline into a liquidity crisis. The sophisticated question is therefore not: "How much can I borrow?" It is: "How much should I borrow, against which asset, under what terms—and what happens if the value of that collateral falls sharply?"
Key Takeaways
- Decoupling Wealth from Cash: Substantial net worth is frequently illiquid; asset-backed borrowing releases working capital while preserving strategic ownership.
- Avoiding Disposal Friction: Borrowing avoids triggering immediate capital gains tax, forfeiting future upside, or ceding corporate control via forced asset sales.
- Securities & Lombard Mechanics: Publicly traded equity and bond portfolios support Lombard loans, but LTVs vary wildly based on asset volatility and concentration.
- Maintenance Margin Call Vulnerability: Market drawdowns can trigger sudden collateral demands, forcing liquidations at market bottoms if borrowing buffers are aggressive.
- Bespoke Physical Collateral: Real estate, aviation fleets, superyachts, and blue-chip art collections can be monetised through specialist private banking desks.
- The Double-Leverage Danger: Borrowing against a volatile portfolio to fund secondary speculative assets compounds downside losses exponentially.
- Pre-Emptive Liquidity Architecture: Establishing credit facilities during balance-sheet strength provides emergency optionality before market volatility emerges.
1. Wealth Is Often Illiquid
Consider a hypothetical entrepreneur with a £200 million net worth. On paper, they are extraordinarily wealthy.
But imagine the balance sheet consists of:
- £120 million in a privately held company;
- £30 million of investment property;
- £25 million in listed securities;
- £10 million in private funds;
- £8 million of art and collectibles;
- and £7 million across other assets and cash.
Now a £10 million investment opportunity appears. The principal has a choice: sell something, or finance the requirement.
This is where structured liquidity becomes relevant. The objective isn't necessarily to increase spending power. It can be to make an illiquid balance sheet financially useful without dismantling it.
2. Why Not Simply Sell?
Sometimes selling is absolutely the correct decision. But there are strategic reasons a principal may prefer not to:
- Appreciation Preservation: Selling a high-conviction, long-term asset forfeits all future capital appreciation.
- Tax Crystallisation: Disposing of appreciated holdings can trigger substantial capital gains tax liabilities depending upon jurisdiction.
- Strategic Control: A founder disposing of equity cedes voting control or dilutes a core strategic stake.
- Irreplaceability: Unique real estate, museum-grade art, or controlling business stakes are non-fungible and hard to reacquire.
- Market Timing Friction: Forcing a rapid sale to meet urgent cash needs often forces acceptance of illiquidity discounts.
Borrowing effectively separates two independent decisions:
$$\text{Decision 1: "I need capital today."} \quad \neq \quad \text{Decision 2: "I want to sell this asset today."}$$
3. Securities-Backed Lending: The Most Familiar Structure
For families with substantial liquid investment portfolios, borrowing against securities can be one of the more straightforward routes to liquidity.
A portfolio of eligible shares, bonds or funds is pledged as collateral. The borrower receives a credit facility based upon a proportion of the eligible collateral value.
The investments remain invested, subject to the particular lending arrangement. This can be attractive because the family doesn't need to liquidate a portfolio simply to raise temporary capital.
But the critical word is: collateral. If the portfolio falls substantially, the lender's position changes.
4. What Is a Lombard Loan?
The term Lombard lending is frequently used in private banking. In broad terms, it describes lending secured against financial assets such as cash, equities, bonds or investment funds.
UBS, for example, describes a Lombard loan as borrowing secured by deposited assets including cash and capital-market instruments. It also explicitly warns that falling collateral values can require borrowers to repay part of the loan or provide additional security.
This is the central characteristic investors need to understand: The credit may appear inexpensive and convenient while markets are stable. Its behaviour can change rapidly during volatility.
5. The Loan-to-Value Ratio
Suppose a family has a £20 million eligible investment portfolio. A lender may be prepared to advance only a proportion of that value. Why? Because the lender needs protection if asset prices fall.
| Collateral Asset Category | Typical Loan-to-Value (LTV) Advance Range | Underwriting & Volatility Characteristics |
|---|---|---|
| Cash & Sovereign Debt | 90% – 95% | Minimal volatility; immediate liquidity; low haircuts. |
| Diversified Equities & IG Bonds | 50% – 70% | Market volatility risk; requires liquid exchange trading. |
| Concentrated Single Stocks | 20% – 40% (or Nil) | High single-issuer risk; subject to daily price swings. |
| Prime Real Estate | 50% – 65% | Requires formal appraisal; transaction execution takes months. |
| Fine Art & Superyachts | 30% – 50% | Bespoke valuation; illiquid exit market; physical custody rules. |
Therefore: £20 million of assets does not necessarily mean £20 million of borrowing capacity. Collateral quality matters.
6. The Danger of the Maintenance Call
This is perhaps the single most important risk in securities-backed borrowing. Consider this sequence:
$$\text{Initial: } \frac{\text{Loan } £8\text{m}}{\text{Portfolio } £20\text{m}} = 40\% \text{ LTV} \quad \xrightarrow{\text{Market Drop}} \quad \text{New: } \frac{\text{Loan } £8\text{m}}{\text{Portfolio } £13\text{m}} = 61.5\% \text{ LTV}$$
The lender may decide that the security supporting the loan is no longer sufficient. The borrower can then be required to:
- contribute additional collateral;
- repay part of the borrowing;
- or face assets being sold.
FINRA specifically warns that securities-backed lines can generate maintenance calls after collateral declines, and that firms may sell securities if borrowers cannot restore the required collateral position.
And notice when this problem occurs: after markets have fallen—exactly when an investor may least want to sell. That is why maximum borrowing capacity should never automatically be interpreted as sensible borrowing capacity.
7. Concentrated Founder Wealth Creates a Different Problem
Now consider the entrepreneur whose wealth is dominated by one company. Their net worth may be enormous, but their collateral diversification is minimal.
This is common among technology founders, business-owning families, and recently exited founders subject to lock-ups or restrictions.
A lender examining concentrated wealth may apply substantially more conservative terms than the headline valuation suggests. Private-company shares introduce even greater complexity because valuation, liquidity and transferability can all be uncertain.
Recent industry reporting shows specialist lenders increasingly examining financing against late-stage private-company holdings, although such structures can involve higher pricing, greater over-collateralisation and potentially equity participation.
This is specialist finance—not a conventional overdraft.
8. Borrowing Against Property
Real estate represents another obvious source of collateral. A family may own primary residences, investment portfolios, commercial real estate, or hospitality assets.
Rather than selling, refinancing can release part of the property's equity. The economics depend upon property valuation, existing debt, income, jurisdiction, asset type, borrower profile, interest rates, and lender appetite.
Unlike listed securities, property does not usually reprice every second. That can reduce daily volatility, but it introduces valuation uncertainty, transaction time, and illiquidity.
9. Borrowing Against Aircraft
A private aircraft can also be financed or refinanced. This is particularly relevant because aircraft combine high capital values with meaningful depreciation and complex international ownership structures.
Specialist lenders consider aircraft type, age, maintenance status, hours/cycles, engine program enrollment, registry, and borrower financial strength.
Both private banks and specialist aviation practices explicitly provide aircraft financing or refinancing services. For the owner, financing preserves capital for core operating investments, but an aircraft's collateral profile requires careful maintenance monitoring.
10. Borrowing Against a Superyacht
The same principle extends to marine assets. A principal may finance the acquisition, construction, refit, or existing equity of a vessel.
J.P. Morgan Private Bank, for example, describes superyacht financing both for purchasing or constructing a yacht and for unlocking liquidity from one already owned.
Marine assets require specialist underwriting: valuation, shipyard reputation, vessel age, flag registry, maintenance class, and international maritime jurisdiction all come into play. A €50 million yacht is a mobile maritime asset subject to an international legal and operational framework.
11. Art Can Become Working Capital
Fine art presents an intriguing liquidity problem. A collection may be extremely valuable, but selling a major work can be undesirable due to emotional attachment, provenance considerations, or tax timing.
Specialist art-backed lending unlocks liquidity while title and ownership are retained.
HSBC Private Banking describes art-secured lending designed to release liquidity from collections, while J.P. Morgan lists fine-art financing among its specialty capabilities. Valuation is critical: because a painting lacks a continuously observable market price, lenders maintain conservative LTVs (typically 30–50%).
12. What About Watches, Cars, Wine and Collectibles?
At the specialist end, other luxury assets can support borrowing: collector cars, significant watches, wine, and jewellery.
Specialist legal and finance practices describe lending structures covering classic cars and high-value collections. However, the fact that something is valuable does not automatically make it good collateral. Lenders care about:
$$\text{Collateral Utility} = \text{Valuation} + \text{Liquidity} + \text{Clear Title} + \text{Physical Custody} + \text{Market Depth}$$
A £1 million asset that can be sold rapidly into a deep market is vastly more financeable than a £3 million niche object with uncertain provenance and few buyers.
13. Private Equity and Fund Interests
Family-office portfolios increasingly contain private-market exposure (private equity, venture capital, hedge funds).
This capital can remain locked up for 7 to 10 years. Certain lenders consider financing against qualifying fund interests or portfolios. HSBC, for example, states that diversified hedge-fund portfolios can be eligible collateral for financing.
Private assets, however, raise issues around valuation lags, transfer restrictions, capital call obligations, and GP consent requirements.
14. Why Would a Family Borrow?
Liquidity serves diverse strategic objectives:
| Liquidity Objective | Strategic Rationale & Execution Profile |
|---|---|
| Opportunistic Acquisition | Rapid deployment for distressed assets or off-market corporate buyouts. |
| Bridge Financing | Interim liquidity ahead of a confirmed PE distribution or business sale. |
| Tax & Estate Obligations | Funding sudden inheritance or cross-border tax liabilities without asset liquidation. |
| Operating Capital Injection | Re-investing into core operating companies without ceding equity stakes. |
The borrowing itself is not the strategy; what the capital achieves is the strategy.
15. The Tax Argument Requires Caution
One frequently cited advantage of borrowing is that accessing loan proceeds avoids the immediate asset disposal that could otherwise crystallise a taxable capital gain.
That can be relevant, but tax outcomes depend upon jurisdiction, residence, domicile, asset type, and interest deductibility rules.
Borrowing should never be reduced to the catchphrase: "Loans avoid tax." That is far too simplistic.
The accurate proposition is: Borrowing can provide liquidity without requiring an immediate taxable disposal, but the complete tax consequences require jurisdiction-specific professional advice.
16. Interest Is the Price of Preserving Ownership
Borrowing avoids selling, but it does not avoid cost. Interest is the obvious price.
Suppose an investor expects an asset to appreciate at 8% annually and can borrow against it at 5%. The spread appears attractive, but neither number is guaranteed.
$$\text{Expected Net Yield} = \text{Asset Return }(8\%) - \text{Borrowing Cost }(5\%) = +3\% \quad (\text{Subject to Market Stress})$$
If the asset drops 20% while borrowing costs rise, the spread evaporates. Borrowers must model stress scenarios.
17. Floating Rates Change the Equation
Many asset-backed facilities are priced relative to benchmark interest rates (SOFR, SONIA, EURIBOR) plus a lender margin.
FINRA notes that SBLOC rates commonly reference benchmarks such as prime or SOFR plus a spread and may change as underlying rates move.
For a £50 million facility, a 200 bps increase in benchmark rates adds £1,000,000 in annual debt service. Sophisticated borrowers evaluate floating-to-fixed hedging and interest-service coverage ratios.
18. The Double-Leverage Trap
There is a particularly dangerous version of asset-backed borrowing: An investor pledges an investment portfolio, borrows against it, and then invests the borrowed money into another speculative asset.
$$\text{Collateral Portfolio Drop} \quad + \quad \text{Leveraged Asset Decline} \quad = \quad \text{Compounded Margin Liquidation}$$
UBS specifically warns that using Lombard borrowing for reinvestment can create leverage that magnifies both gains and losses. This is fundamentally different from using short-term borrowing to bridge a predictable liquidity event.
19. Cross-Collateralisation: Convenience With Consequences
A lender may consider several assets together: investment portfolio, property, cash, and art.
This improves borrowing capacity or terms, but families must understand precisely what has been pledged. Cross-collateralisation creates dependencies between previously isolated assets.
A problem in one asset class can spill over to encumber the entire portfolio.
20. Liquidity Should Be Designed Before It Is Needed
The worst time to look for liquidity is when it has suddenly become essential. Urgency weakens negotiating power, asset markets may be falling, and lenders become risk-averse.
Sophisticated families establish credit architecture while their balance sheets are strong. That means mapping out financeable assets, pre-negotiating terms, and holding pre-approved standby facilities.
21. The Family Office Liquidity Ladder
Rather than borrowing reactively, a family office should establish a liquidity hierarchy:
| Tier Level | Asset Collateral Class | Execution Speed & Complexity |
|---|---|---|
| Tier 1 | Cash & Cash Equivalents | Immediate; zero execution complexity. |
| Tier 2 | Liquid Securities (Lombard SBLOC) | 1 to 3 Days; standardized documentation. |
| Tier 3 | Unencumbered Real Estate Refinance | 30 to 90 Days; requires appraisal & legal title check. |
| Tier 4 | Private Fund / PE LP Interests | 60 to 120 Days; requires GP consent & fund valuation. |
| Tier 5 | Luxury Assets (Art, Jets, Yachts) | Complex; bespoke underwriting and physical verification. |
22. When Borrowing Makes Sense
Asset-backed borrowing is rational when:
- the liquidity requirement is temporary;
- the collateral is robust and diversified;
- leverage (LTV) is conservative (<40%);
- cash flow comfortably services interest;
- selling would disrupt a core long-term strategy;
- and a credible, pre-funded repayment plan exists.
A facility without an intended exit can quietly become permanent, drag-on-equity leverage.
23. When Selling May Be Better
Debt is not automatically sophisticated. Sometimes the sophisticated decision is to sell.
Selling is preferable when:
- the asset no longer fits long-term investment criteria;
- current valuations represent historical peaks;
- borrowing costs exceed realistic asset returns;
- existing overall balance-sheet leverage is already high;
- or repayment relies on optimistic future asset sales.
Preserving ownership at any cost is an emotional trap. Liquidity should sometimes come from reallocation, not leverage.
24. Questions Every Family Office Should Ask Before Borrowing
Before executing an asset-backed facility, family office boards should mandate answers to thirteen operational questions:
- 1. What is the capital actually required for?
- 2. How long will the debt remain outstanding?
- 3. Which specific assets are being pledged?
- 4. How volatile is the underlying collateral?
- 5. What is the initial Loan-to-Value (LTV)?
- 6. At what exact valuation threshold does a maintenance margin call trigger?
- 7. Can the lender unilaterally alter haircuts or eligible collateral rules?
- 8. Is the interest rate fixed, floating, or capped?
- 9. What unencumbered secondary collateral is available during market drawdowns?
- 10. Can the lender sell assets without prior borrower consent during a margin default?
- 11. Are assets cross-collateralised across multiple entities?
- 12. What happens on death, incapacity, or change of control?
- 13. What is the pre-planned, stress-tested repayment exit strategy?
And most importantly: Can we comfortably service this loan if the collateral value drops 30% while borrowing costs rise by 200 bps simultaneously?
25. Frequently Asked Questions
Q: Can wealthy individuals borrow against their assets instead of selling?
A: Potentially, yes. Depending upon the asset and lender, financing can be secured against securities, property, aircraft, yachts, art and certain investment interests. Eligibility and terms vary materially.
Q: What is a securities-backed line of credit?
A: It is a credit facility secured against eligible securities in an investment account. If collateral falls below required levels, borrowers may need to add assets or repay debt; otherwise securities may be sold.
Q: What is a Lombard loan?
A: A Lombard loan is generally a loan secured against financial assets such as cash, equities, bonds or fund units deposited with the lender.
Q: Can you borrow against art?
A: Specialist art-secured lending exists, subject to valuation, ownership, documentation, lender appetite and other conditions.
Q: Can you borrow against a yacht or private jet?
A: Specialist financing and refinancing structures exist for both aircraft and superyachts.
Q: Why borrow rather than sell investments?
A: Potential reasons include preserving long-term investment exposure, avoiding an immediate disposal, bridging a temporary capital requirement or financing another opportunity. The costs and risks of borrowing must be weighed against the consequences of selling.
Q: What is the biggest risk?
A: For marketable securities, collateral deterioration can be particularly important because it may trigger additional collateral requirements or forced asset sales during falling markets. Other asset classes introduce their own valuation, liquidity and enforcement risks.
26. Institutional Glossary
- Securities-Backed Lending (SBLOC) / Lombard Lending
- Credit facilities granted by private banks or institutions using liquid financial portfolios (equities, bonds, funds) as pledged collateral.
- Loan-to-Value (LTV) Ratio & Advance Rate
- The percentage proportion of a collateral asset's total market value that a lender is willing to advance as debt.
- Maintenance Margin Call
- A legal mandate issued by a lender requiring a borrower to deposit additional cash/collateral or face forced liquidation when collateral asset prices drop below contractual thresholds.
- Double-Leverage Trap
- The compounding risk exposure created when capital borrowed against an existing volatile asset is deployed into a second speculative investment.
- Cross-Collateralisation
- Pledging multiple distinct asset classes (e.g., real estate, equities, and art) to support a single comprehensive debt facility.
27. Institutional Verification & Advisory Standards
For family office CFOs, private bankers, and credit fiduciaries, structured liquidity arrangements should be cross-referenced against established regulatory and banking standards:
| Governance Dimension | Governing Body / Regulatory Code | Primary Standard & Verification Protocol |
|---|---|---|
| Securities Credit Regulations | FINRA / SEC / FCA Credit Frameworks | Margin Requirements, Maintenance Calls & Collateral Haircut Directives. |
| Private Banking Credit Standards | Basel III / Prudential Regulation Authority (PRA) | Lombard Lending Capital Adequacy & Counterparty Credit Risk Standards. |
| Specialist Asset Appraisal | RICS / ISTAT / Royal Institute of Appraisers | Formal Valuation Standards for Real Estate, Fine Art, Aviation & Marine Collateral. |
28. The APX Perspective
For UHNW families, liquidity management is not simply about maintaining a large cash balance. Too much idle cash carries its own drag on returns.
The sophisticated objective is to construct a balance sheet in which capital can be accessed without forcing strategically poor decisions.
That may involve securities-backed lending, real estate refinancing, or specialist financing against art, aircraft, or superyachts. Or the correct decision may be to sell.
$$\text{Core Financial Objective} = \text{Strategic Optionality } (\text{Not Unfunded Leverage})$$
The strongest balance sheet is not necessarily the one with zero debt. It is the one that can access liquidity on acceptable terms without surrendering control of strategically important assets at precisely the wrong moment.


